Banks are moving quickly from experimenting with artificial intelligence to embedding it in the way work gets done. Predictive models already influence lending, fraud detection, collections, customer retention, and pricing. Generative AI is entering servicing, sales, compliance, and operations. Now agentic AI is beginning to connect these capabilities and take action across workflows with increasingly limited human involvement.
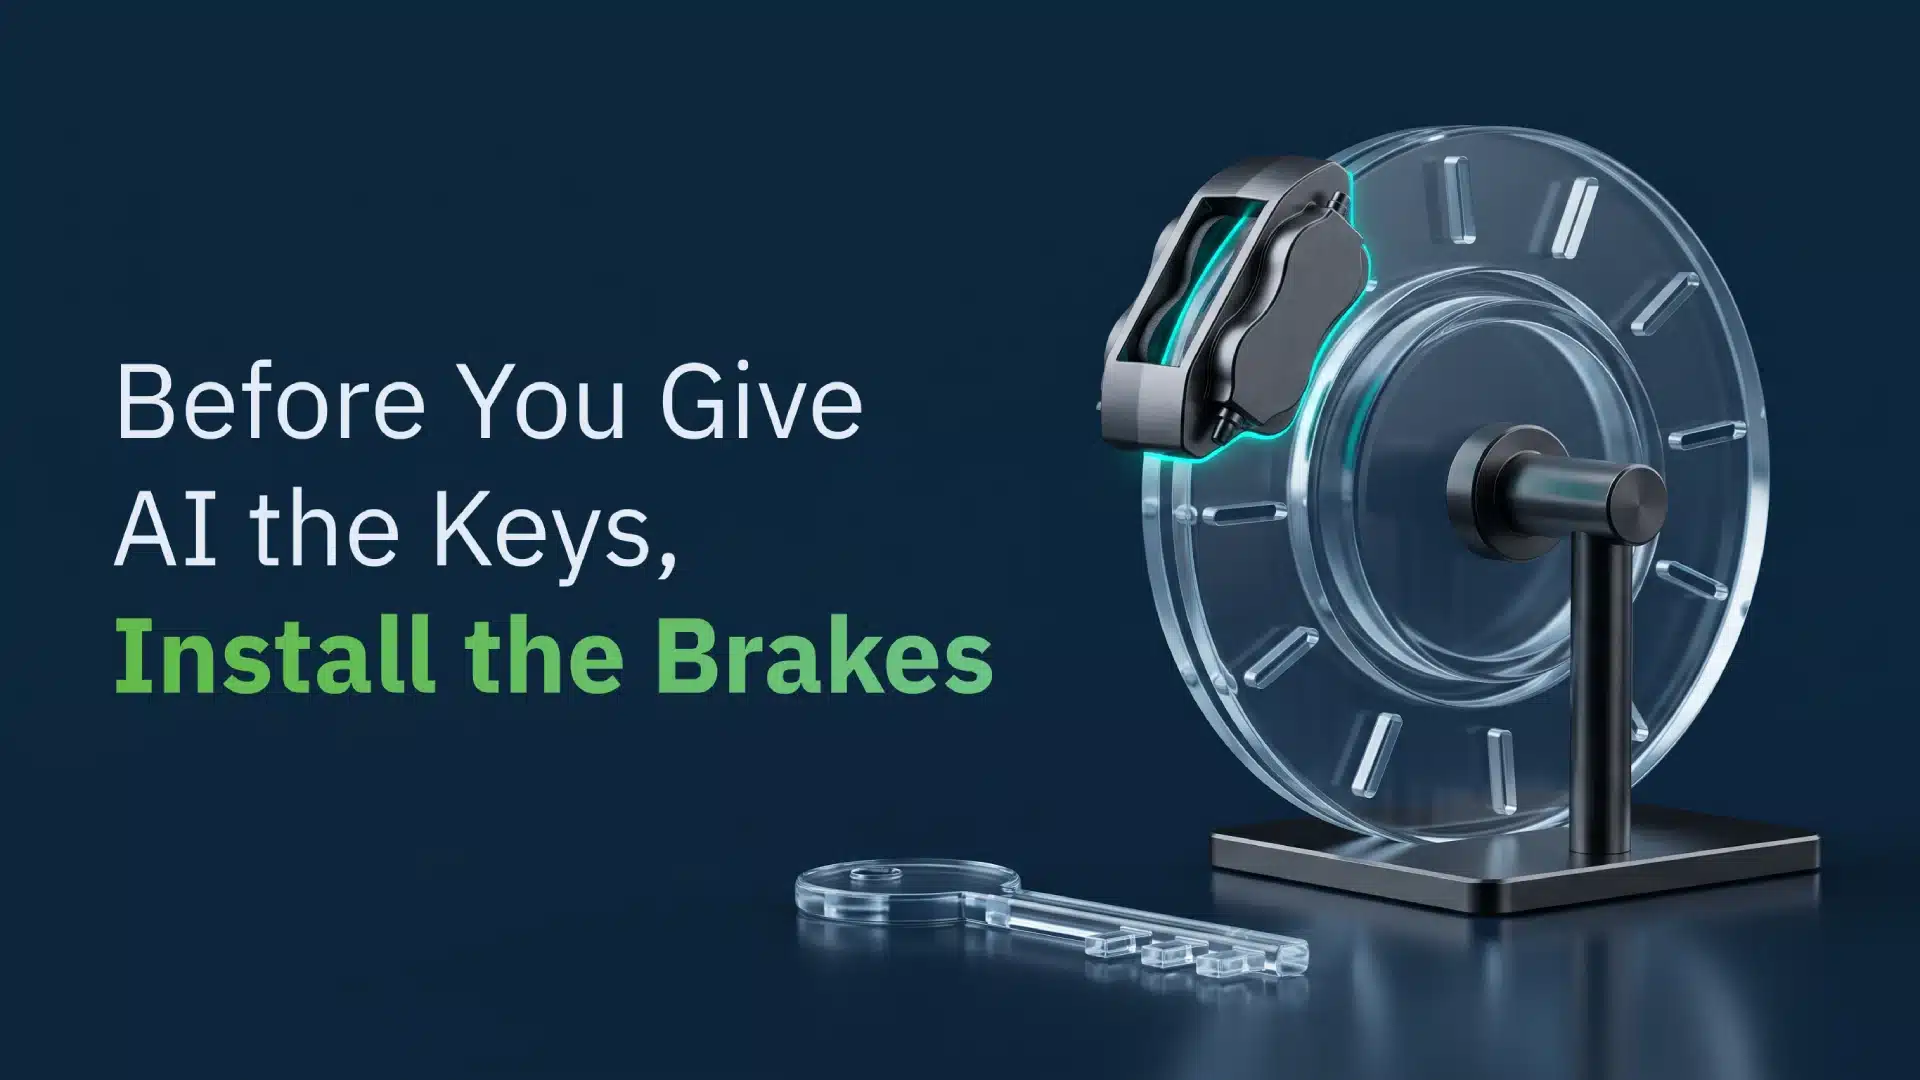
This creates enormous opportunity, but also a new management problem. The central question is no longer simply whether an AI system can make a good recommendation. It is whether the institution can retain control when that system begins to act autonomously. As banks give AI more authority, they need an equally strong capability to constrain, suspend, or reverse that authority. Before you give AI the keys, install the brakes.
AI Is Moving From Advice to Action
Traditional AI was largely advisory. A model predicted whether a customer might default, whether a transaction was suspicious, or whether a depositor was likely to leave. A human or downstream system typically decided what happened next. Generative AI expanded the role of machines by allowing them to communicate, summarize information, create content, and interact with customers and employees.
Agentic AI represents a more consequential shift. An agent can potentially determine what action to take, invoke another system, contact a customer, make an offer, change a workflow, trigger another agent, or execute a task. When a predictive model is wrong, the result may be a poor recommendation. When an autonomous agent is wrong, the institution can act incorrectly at scale. The risk has moved beyond model accuracy to operational authority.
“When an autonomous agent is wrong, the institution can act incorrectly at scale.”
Autonomy Requires a Different Kind of Control
Banks already understand the importance of controlling systems that operate at scale. Payments have transaction limits. Trading environments have circuit breakers. Credit processes have approval thresholds. Cybersecurity teams can isolate compromised infrastructure. These mechanisms are not evidence that institutions distrust technology. They are what allow institutions to use powerful technology safely.
AI should be treated the same way. Yet much of the discussion around responsible AI continues to center on model validation, explainability, bias, and human oversight. These remain essential, but autonomous AI introduces another risk: delegated authority. The more authority an institution gives an AI system, the more explicitly it must define the boundaries of that authority.
The answer cannot simply be to “keep a human in the loop.” A human may technically participate in a workflow without exercising meaningful control. If someone recognizes problematic behavior but lacks the authority or technical ability to stop it, oversight offers little protection. Human oversight matters only when humans retain the ability to intervene.
“Human oversight matters only when humans retain the ability to intervene.”
Don’t Build a Kill Switch. Build Brakes
The term “kill switch” suggests a binary decision: the AI is either running or it is shut down. Banks need something more sophisticated. They need mechanisms that can progressively reduce autonomy as risk increases.
Under normal conditions, an AI agent might execute approved actions autonomously. If unusual behavior appears, the bank could increase monitoring. If risk indicators deteriorate further, the agent’s authority could be restricted by transaction value, customer segment, product, geography, or type of action. At a higher level, the system might revert to requiring human approval. If the problem persists, the agent could be isolated while the underlying process returns to a rules-based or manual workflow.
This creates an AI control plane rather than a simple on-off mechanism. More importantly, the rules governing that control plane should be established before something goes wrong.
Consider a collections agent that determines whom to contact, when to contact them, which channel to use, and what treatment to recommend. If customer complaints rise sharply, promises to pay decline, contact frequency changes unexpectedly, or certain customer groups begin receiving materially different treatment, the institution should not have to wait for someone to notice. Those conditions should already be defined as tripwires that reduce the agent’s autonomy or trigger human intervention.
The same principle applies elsewhere. A deposit agent might be constrained when offer economics fall outside approved limits. An underwriting agent might lose decision authority when model confidence declines. A servicing agent might be prevented from communicating autonomously when factual error or complaint rates exceed acceptable thresholds. The institution should determine when AI must slow down before it needs to slow down.
“The institution should determine when AI must slow down before it needs to slow down.”
Predictive Intelligence Can Monitor AI Itself
This also expands the role of predictive intelligence. Banks have traditionally used predictive models to anticipate customer behavior, credit outcomes, fraud, attrition, and other business events. In an agentic environment, predictive intelligence can also help determine whether an AI system itself is behaving as expected.
The institution can continuously compare predicted and actual outcomes. Is a collections strategy producing the expected promises to pay? Are retention offers delivering the anticipated economics? Are false positives in fraud rising beyond expected levels? Are customer complaints increasing faster than forecast?
The same intelligence used to optimize the business can become part of the safety architecture governing AI. In effect, AI will increasingly be used to monitor AI. But the final authority should remain clearly assigned to people.
Banks May Need a New Role: The AI Controller
That leads to an organizational question that has received far less attention than the technology itself: who is responsible for controlling autonomous AI?
Banks already have chief risk officers, CIOs, data leaders, model risk teams, compliance functions, cybersecurity organizations, and increasingly chief AI officers. But autonomous AI crosses the boundaries between all of them. An AI agent may simultaneously involve a business process, predictive models, an LLM, customer data, APIs, third-party systems, and regulatory obligations.
Banks may therefore need a new role: the AI Controller.
The AI Controller would not necessarily be a new C-suite executive. In many banks, it could be a designated function within existing risk, technology, or AI governance structures. What matters is the mandate. The AI Controller would know which autonomous systems are operating, what authority each has been granted, what limits apply, and what conditions should reduce or withdraw that authority.
Most importantly, the AI Controller must have the authority to act. The role should be able to move an agent from autonomous execution to human approval, quarantine a problematic agent, or suspend autonomous activity when defined thresholds are breached. It should also oversee the process for restoring autonomy once the issue has been resolved.
Think of the role as analogous to an air traffic controller. The controller does not fly the aircraft or decide where passengers want to go. But the controller understands what is operating within the environment, establishes boundaries, identifies emerging conflicts, and has the authority to intervene before a problem becomes a crisis.
From Model Governance to Autonomy Governance
Banks have spent years building model risk management disciplines. They validate models, document assumptions, monitor performance, assess drift, and test for bias. Those practices will remain important, but agentic AI requires institutions to govern something broader than models. They must govern autonomy.
For every material AI agent, a bank should be able to answer a basic set of questions: What decisions can it make? What systems and data can it access? What actions can it execute? What limits apply? What conditions reduce its authority? Who can suspend it? And how does the organization continue operating if the agent is removed?
These are not merely technical questions. They are questions of accountability and operating design. This is why autonomy governance will become increasingly important as banks move from deploying individual AI applications to operating interconnected ecosystems of models and agents.
Control Will Enable Greater Autonomy
The case for AI brakes is not an argument against autonomous AI. It is the opposite. Institutions will be more comfortable giving AI meaningful responsibility when they know that responsibility can be reduced quickly when necessary.
Financial markets have circuit breakers because they operate at enormous scale and speed. Payment networks have transaction limits because payments need to happen quickly without surrendering control. Cybersecurity teams can isolate infrastructure because containment enables organizations to keep operating during an incident. Controls make powerful systems more usable, not less.
The same will be true of AI. Banks that develop effective mechanisms for observing, constraining, and, when necessary, stopping autonomous systems will ultimately be able to give those systems more freedom than institutions that rely on loosely defined human oversight.
The banking industry’s AI conversation has moved rapidly from models to large language models and now to agents. The next stage will be about governing intelligence at scale. That will require observability, predictive intelligence, auditability, intervention, and clear human authority.
The most sophisticated AI capability in a bank may therefore not be the agent that knows what action to take. It may be the control system, and the person behind it, that knows when the agent should no longer be allowed to take that action.
Banks should embrace autonomous AI. But autonomy should never mean surrendering control.
“Before you give AI the keys, install the brakes.”