Loss Mitigation Under NCUA Examination

Credit union loss mitigation under NCUA examination, highlighting Supervisory Letter 13-02 workout policy, the shift from TDR to ASC 310-20, modification-frequency limits, and 2026 priorities.

TL;DR A credit union’s loss mitigation policy was likely written against a letter that is only half current. NCUA Supervisory Letter 13-02 still governs what examiners expect in a workout policy today. One piece of that same letter, the TDR classification and reporting requirement, has not applied as written since credit unions adopted CECL. This […]

Core Deposit Analytics for Community Banks
Core deposit analytics for community banks, highlighting the FFIEC core deposit definition, the $250,000 insured threshold, call report blind spots, and continuous account-level classification.

TL;DR A community bank already reports a core deposit number every quarter. Almost none of them can say, on any given day between those reports, exactly which accounts are driving it. This piece lays out what the FFIEC counts as a core deposit, why that definition is harder to apply than it looks, and what […]

NCUA 2026 Supervisory Priorities: The Delinquency Line
NCUA 2026 supervisory priorities on delinquency, highlighting sufficiency of credit administration, examiner expectations at decade-high delinquency rates, and where prediction fits for credit unions.

TL;DR A credit union does not get to choose whether delinquency becomes an exam topic this year. NCUA already decided that for every federally insured institution, in writing, at the start of the year. Letter 26-CU-01 names the number, states it plainly, and tells examiners where to look. This piece lays out exactly what the […]

Insurance Analytics and AI: A Practical Map
Insurance analytics and AI use cases, highlighting a two-question oversight map, low-oversight zones where teams move fast, and high-oversight decisions like underwriting declines, claims denials, and fraud.

TL;DR Most guides to insurance analytics and AI organize their content the same way: a chapter on underwriting, a chapter on claims, a chapter on distribution. That structure describes what each use case does. It says almost nothing about what two projects in the same chapter can require of a team, because a model that […]

Why “AML Platform” Means Something Different to Every Vendor
AML platform evaluation for banks and credit unions, highlighting the three product categories vendors sell, existing compliance stacks, decommissioning scope, explainability, and deployment speed.

TL;DR Ask three AML vendors what their “platform” covers and you get three different answers. One vendor means a full compliance suite, sanctions screening, transaction monitoring, case management, and SAR filing, all under one roof. Another means a monitoring or risk-scoring engine built to plug into a suite the institution already runs. A third means […]

How AML Fraud Detection Cuts False Positives Without Missing Real Cases
AML fraud detection, highlighting how rule-driven alert backlogs form, the risk of tightening rules, risk-based scoring that cuts false positives, and the evidence examiners still expect.

TL;DR An AML program built on static threshold rules learns to flag a wire over a set dollar amount, a transaction matching one of several typologies, a pattern that fits a published red flag. None of those rules check whether this specific transaction, from this specific customer, with this specific history, looks like anything beyond […]

Why AI-Powered Document Fraud Detection Catches What a Checklist Misses
AI-powered document fraud detection, highlighting why manual review and static checklists miss altered paperwork, field-by-field scoring, examiner-ready flags, and production results for banks.

TL;DR A forged pay stub or an altered bank statement can clear a human reviewer’s checklist without raising a flag, because the checklist confirms a document exists and looks right. It does not confirm that the income figure on the pay stub matches the deposits on the bank statement, or that the applicant behind both […]

What Changes When You Move Predictive Analytics From a Bank to an Insurer
Predictive analytics solutions for banks and insurers, highlighting how use cases differ by vertical, what carries over between deployments, what to check before reusing a solution, and credit decisioning results.

TL;DR A bank buys predictive analytics to score credit risk, catch fraud, and predict which deposits are about to walk. An insurer buys it to triage claims, underwrite policies, and catch a renewal before it lapses. The outcomes look nothing alike, which is why so many buyers assume the software underneath has to be different […]

What Predictive Analytics Software Has to Do Inside a Regulated Institution
Predictive analytics software for regulated institutions, highlighting the four use cases that pay off, explainability for examiners, build, buy, or augment decisions, platform evaluation, and fraud detection proof.

TL;DR Predictive analytics software has one job inside a bank, insurer, or lending institution that it does not have anywhere else. It has to score a borrower, a claim, or a transaction accurately, then show its work to a risk committee, an internal auditor, or an examiner who asks why the model said what it […]
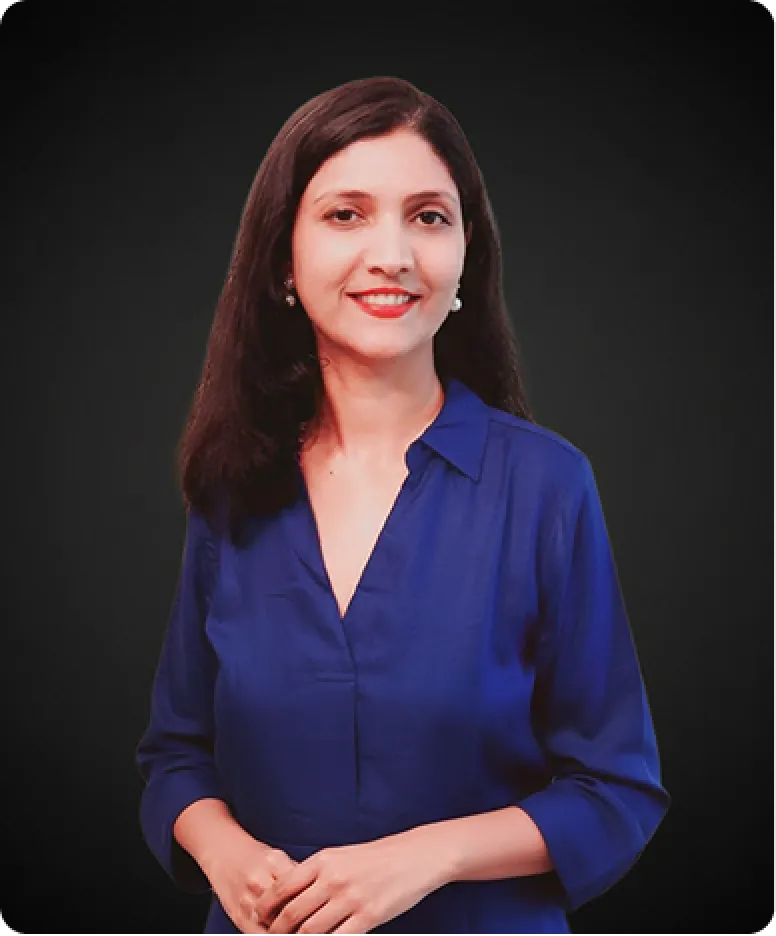
Tarika Bhutani

Senior Director – Sales and Marketing Operations

Tarika is a market development leader driving global growth through strategic partnerships and go-to-market initiatives.


She focuses on expanding enterprise adoption of AI solutions across international markets, working closely with partners and clients to enable data-driven transformation.


Her work centres on scaling enterprise AI through partner-led growth and direct customer engagement, supporting organisations in implementing impactful, data-driven solutions worldwide.

Rajnish Ranjan

Vice President, Head – Data Science

Rajnish brings over two decades of experience leading data-driven transformation across Fortune 500 organisations.


His career spans senior roles at HSBC, Zafin, Cisco, TCS, Nielsen, iQuanti, Symphony, Supervalu, and Harman, delivering measurable cost savings, operational efficiencies, and revenue growth.


With experience across banking, retail, telecom, pharma, CPG, and digital marketing, he leads cross-functional teams at iTuring.ai to deliver advanced analytics, machine learning, and AI solutions.

Aishwarya Hegde

VP Operations & Content Head

Aishwarya has been instrumental in building iTuring.ai from inception and continues to manage core operations across the organisation. Her responsibilities span project operations, financial planning, and evaluating future expansion opportunities.


Prior to iTuring.ai, she worked with Market Probe and WNS Research & Analytics, delivering high-impact decision support and actionable analytics for IBM with a record of zero errors.


Aishwarya holds a postgraduate degree in Data Science and Machine Learning from Manipal University.

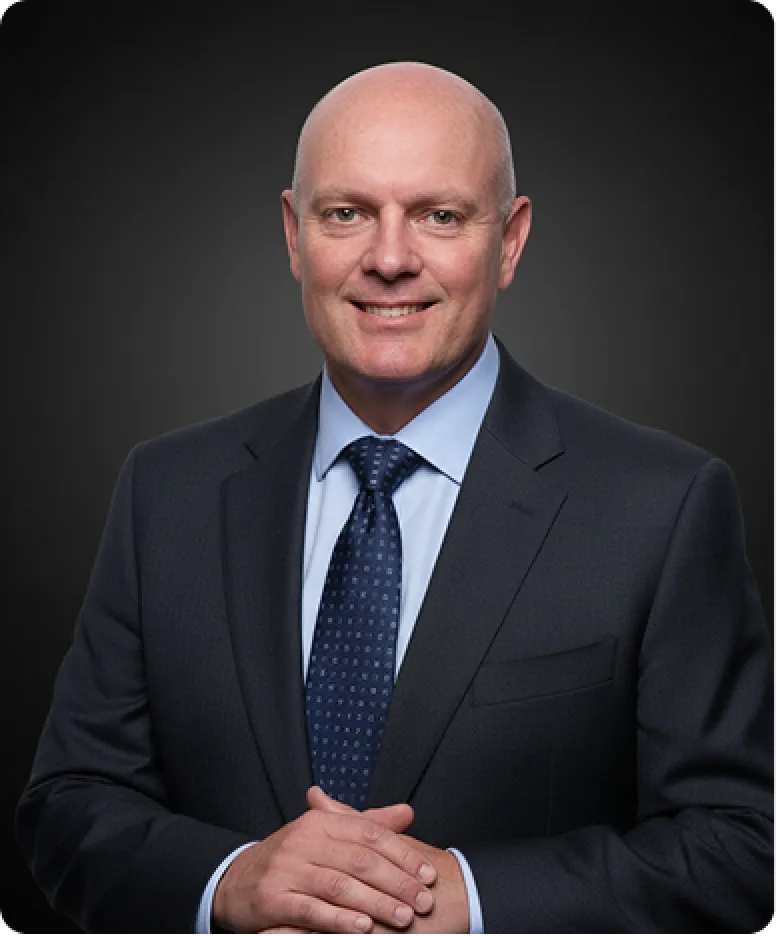
Bryan McLachlan

Managing Director – Africa

Bryan has 30 years of experience driving innovation and growth across technology, banking, insurance, and retail.


Prior to iTuring.ai, he held executive leadership roles at Instant Life, AIG, Nedbank, FNB, and TransUnion. He focuses on enabling enterprises to adopt AI and machine learning within trusted, governed, and risk-managed frameworks.


Bryan holds a Master’s degree in Commerce from the University of Johannesburg.

Mohammed Nawas M P

Co-Founder, VP Product Development

Nawas brings 20 years of experience in designing and delivering cloud-native software and data systems. He has held senior technology roles at HCL, Radisys, Kyocera, and Mindtree, leading large development teams and complex product builds.


At iTuring.ai, he oversees product roadmap and customer delivery, applying cloud-first thinking, deep systems expertise, and a focus on building robust, scalable AI solutions that challenge industry norms.


He is a graduate of Rajiv Gandhi Institute of Technology.

Amit Kumar

Amit is a technology architect with over 18 years of experience designing data-intensive systems and enterprise analytics platforms. He has built highly scalable products across open architecture models and virtualised infrastructure, aligning deep technical detail with business requirements for AI and ML solutions.


Prior to iTuring.ai, he held senior technical roles at Radisys and Aricent. Amit leads platform architecture with a focus on governance, lineage, and traceability.


He holds a First Class with Distinction BTech in Computer Science from Cochin University.

Valsan Ponnachath

President, COO and Co-founder

Valsan brings over two decades of global leadership across sales, professional services, and product operations in technology and SaaS enterprises.


Prior to iTuring.ai, he held senior executive roles at Fiserv, Cisco, and Sun Microsystems, most recently serving as Senior Vice President at Fiserv overseeing global system integration and international professional services. Based in California, he leads iTuring.ai’s growth in the Americas.


Valsan holds an MBA from the University of Nebraska and a BE in Computer Science from Bangalore University.

Suman Singh

Founder & CEO

Before founding iTuring.ai in 2018, Suman led analytics at Zafin and Fiserv as CAO and General Manager Analytics, delivering enterprise-scale solutions still running in production.


His work includes fraud detection systems saving clients over $19M, patented Customer Relationship Score methodology, and price optimisation recognised by the INFORMS Edelman Award (2014). He has authored multiple research papers and pioneered the data-to-value approach.


Suman holds a Master’s in Statistics from CCS HAU and a Bachelor’s in Agricultural Engineering from BHU.